Description
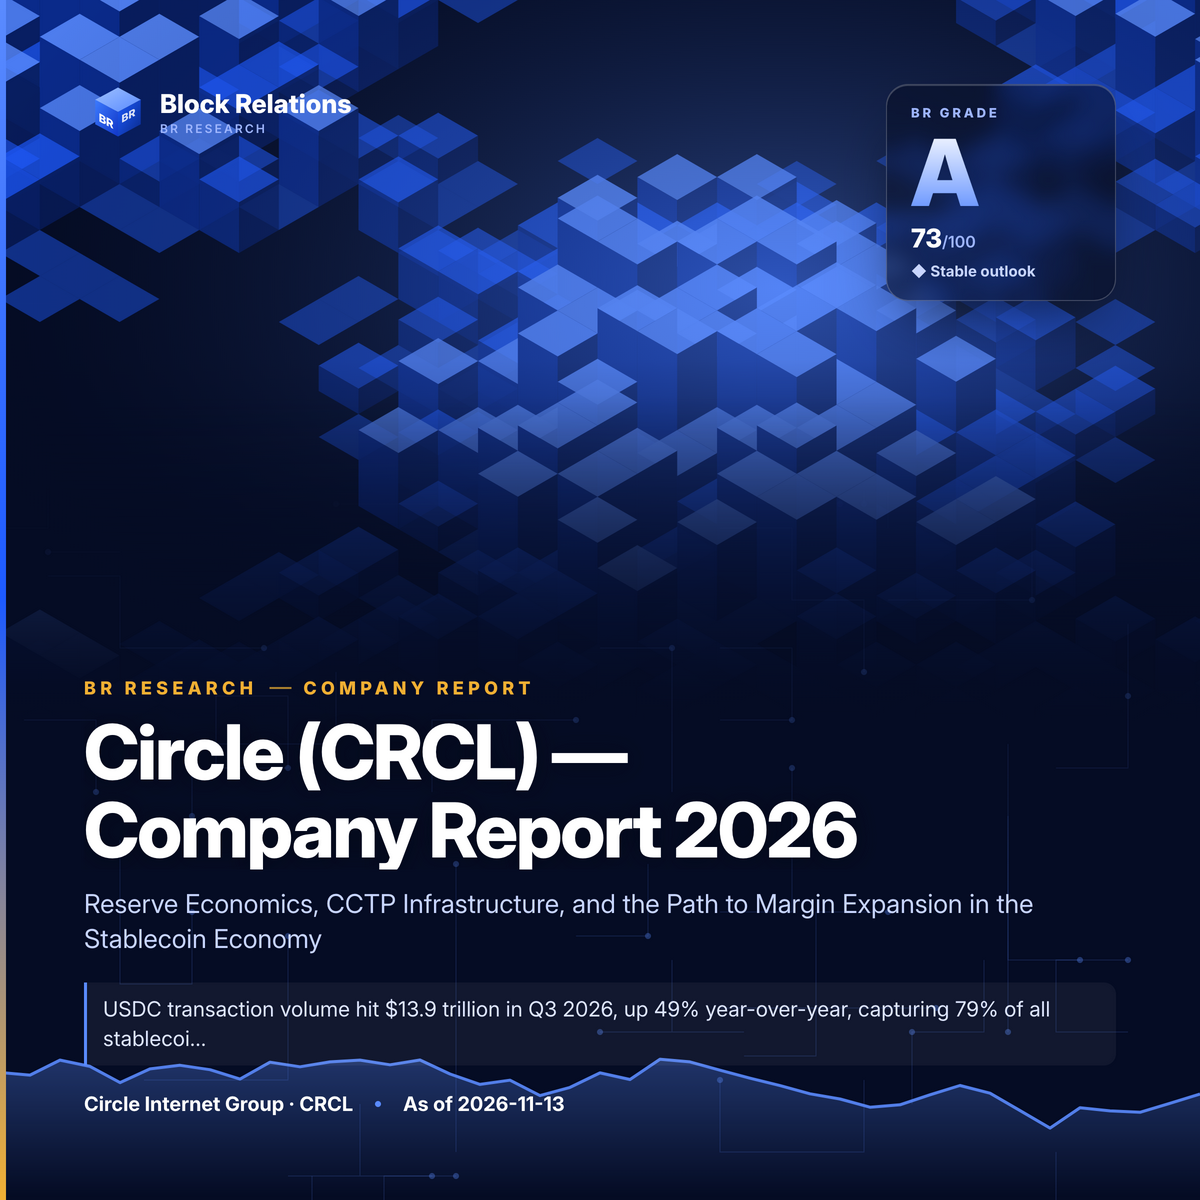
Circle Internet Group (CRCL), a public fintech company trading on the NYSE since June 2025, has built the world’s most-used stablecoin by transaction volume—USDC carries 79% of all stablecoin transactions on just 28% of market-cap share. Circle’s business model is anchored in reserve income: $2.64B annually in FY 2025 (96% of total revenue) generated from holding short-term U.S. Treasuries backing $73.9B in USDC circulation. However, the company faces a critical challenge: Coinbase captures 56% of gross reserve income through a revenue-share agreement renewed through 2029, and interest-rate sensitivity means every 100 basis points of rate decline swings revenue by $618M. This report examines Circle’s defensible moat (CCTP V2’s burn-and-mint protocol across 27+ blockchains), emerging revenue diversification (CPN payments at $41.3B annualized TPV, Arc mainnet with 100+ institutional builders), regulatory tailwinds (GENIUS Act framework enacted July 2025), and the path to margin expansion as distribution partnerships scale. For institutional investors and allocators, the key question is whether Circle’s 79% transaction-volume share can sustain in a flat-circulation environment ($73.9B Q3 2026 vs. $73.3B Q2) and whether margin expansion materializes as non-reserve revenue streams grow.

Reviews
There are no reviews yet.